Key points
- How Jensen Huang describes Nvidia's sources of demand
- What Nvidia's filings show about its buyers
- Where Nvidia stock stands after a rough week
Nvidia (NVDA) chief executive Jensen Huang says computing workloads that don't depend on AI labs account for roughly a third of its business and are growing about 30% to 40% a year.
Huang also described demand from frontier AI labs and startups that rent Nvidia compute. He spoke on the BG2 podcast with Brad Gerstner, founder of Altimeter Capital, in an episode posted Oct. 15.
How Huang describes the three groups
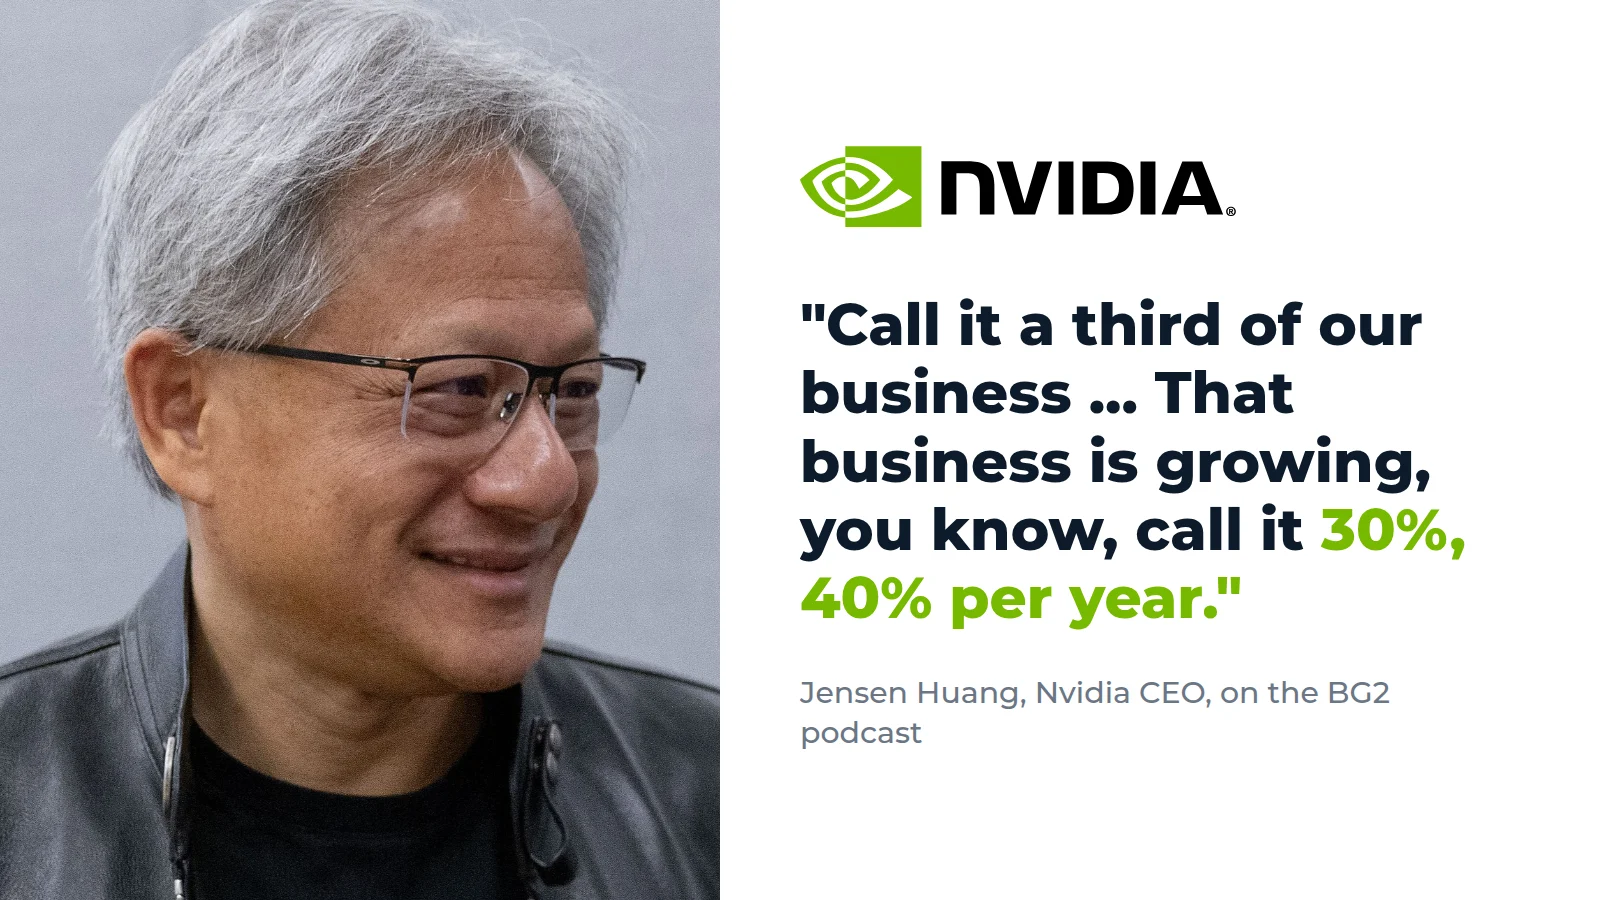
Huang described the first segment as "just baseline computing," used for data processing, molecular dynamics, physics simulation, and quantum chemistry. It also includes older machine learning, such as "XGBoost at Visa, MasterCard, you know, for fraud detection," and recommender systems. "Call it a third of our business," Huang said, adding that "that business is growing, you know, call it 30%, 40% per year."
"In the absence of any AI labs, Nvidia is not zero," Huang said.
On the labs, Huang said "people see two, but we work with every one of them," pointing to Meta's Muse models, xAI's Grok, Google's Gemini, and Anthropic. He put the group at "not quite one-third of our business and let's say a quarter of our compute."
The third group is startups. "Because we're at the beginning of a new computing platform shift, just a vast number of new startups are coming out," Huang said, citing consumer companies, physical and biological AI, materials science, and Jeff Bezos's new company, Prometheus. "The number of companies across the spectrum of industries that have been started, thousands of them, and what do they do? They rent Nvidia compute. So they're renters." He called that group "cloud computing for the next generation."
Huang says Nvidia sells more into each gigawatt
Huang said Nvidia's market share is rising partly "because we offer so much more per gigawatt than we used to." "We used to be a GPU company, then we became the largest and fastest growing networking company," he said. "We're now going to be one of the largest CPU companies, surely the fastest growing one."
He estimated that what Nvidia sells into one gigawatt of data center capacity has grown from about $18 billion to more than $40 billion, as the company added storage and security products. "My sense is that that's going to keep on going up," he said.
Huang said Nvidia's share of spending was in single digits six years ago. He put it at probably about 40% of the big cloud providers' capital spending today and about 80% outside them, including on-premises data centers and neoclouds.
What Nvidia's filings show
Nvidia doesn't report a classical computing segment, so Huang's split can't be checked directly against its results. This fiscal year, Nvidia began dividing data center revenue by type of buyer instead.
In the quarter ended July 26, revenue from the public clouds and the largest consumer internet companies, which Nvidia calls Hyperscale, was $48.7 billion. Revenue from AI cloud providers, industrial companies, and enterprises rose 138% from a year earlier to $40.3 billion, according to Nvidia's quarterly filing. That group made up 45.3% of data center revenue, up from 41.2% a year earlier.
Nvidia credited that growth to "end-demand from AI natives, enterprises, and sovereign customers, as well as hyperscalers utilizing AI clouds." Huang's categories don't map directly onto Nvidia's reported buyer groups. A hyperscaler can buy chips for both recommender systems and frontier AI models.
Where Nvidia stock stands
Nvidia closed at $214.13 on Friday, Oct. 16, up 14.8% from its 2025 close of $186.50. The stock is 10.5% below its 2026 closing high of $239.24, set on Oct. 6, after falling 6.6% this week as chip stocks sold off.
At Friday's close, Nvidia traded at about 13.5 times analysts' average earnings estimate for its fiscal year ending in January 2028, based on Yahoo Finance estimates. Bank of America analyst Vivek Arya said on Friday that Nvidia, Broadcom, and Micron already trade like Cisco after the dot-com crash. "Investors are paying post-crash multiples for a cycle that hasn't crashed," he wrote.
Nvidia reports third-quarter results on Nov. 17. Analysts expect revenue of about $109 billion, according to our earnings calendar.