Key points
- Junk bonds are having a rough September
- Rising rates explain part of the selloff
- Where I'd watch for credit stress
Junk bonds are headed for their worst month since 2022. Two popular junk-bond ETFs, iShares iBoxx $ High Yield Corporate Bond ETF (HYG) and SPDR Bloomberg High Yield Bond ETF (JNK), lost more than 2% in September through Monday on a total return basis.
Junk bonds are issued by companies with below-investment-grade credit ratings. Investors demand higher yields because there's a greater risk they won't be repaid.
A sharp selloff might suggest those repayment worries are growing. But rising interest rates also push bond prices down, and the losses extend well beyond junk. That's why I'd be careful about reading this as a credit scare.
How rising rates are hitting bonds
The Vanguard Total Bond Market ETF (BND), which holds Treasurys, mortgage bonds, and investment-grade corporate debt, fell 2.4% in September through Monday, about as much as the junk funds. The iShares 20+ Year Treasury Bond ETF (TLT) lost 4.4% over the same period. Both junk ETFs are still clinging to small gains for 2026, while BND is down 2.5% for the year.
Those losses show that even bonds with less default risk are under pressure. But the funds differ in their sensitivity to interest rates, so comparing their returns doesn't isolate concerns about repayment. To judge whether investors are also becoming more worried about risky borrowers, I'd look at credit spreads: the extra yield they demand over Treasurys.
The rate side is easy to see. The Federal Reserve raised rates this month for the first time since 2023, and the 10-year Treasury yield settled at 5.241% on Monday, its highest close since June 2007. Rebecca Venter, a senior fixed-income client portfolio manager at Vanguard, put it simply: "The move in rates is really what's driving returns, primarily."
Where credit stress could show up
The pressure builds when companies need to borrow again. Their existing fixed-rate debt carries the same interest payments, but refinancing at higher rates can leave them with a bigger bill. Venter warned that those costs could eventually become harder for the riskiest borrowers to handle.
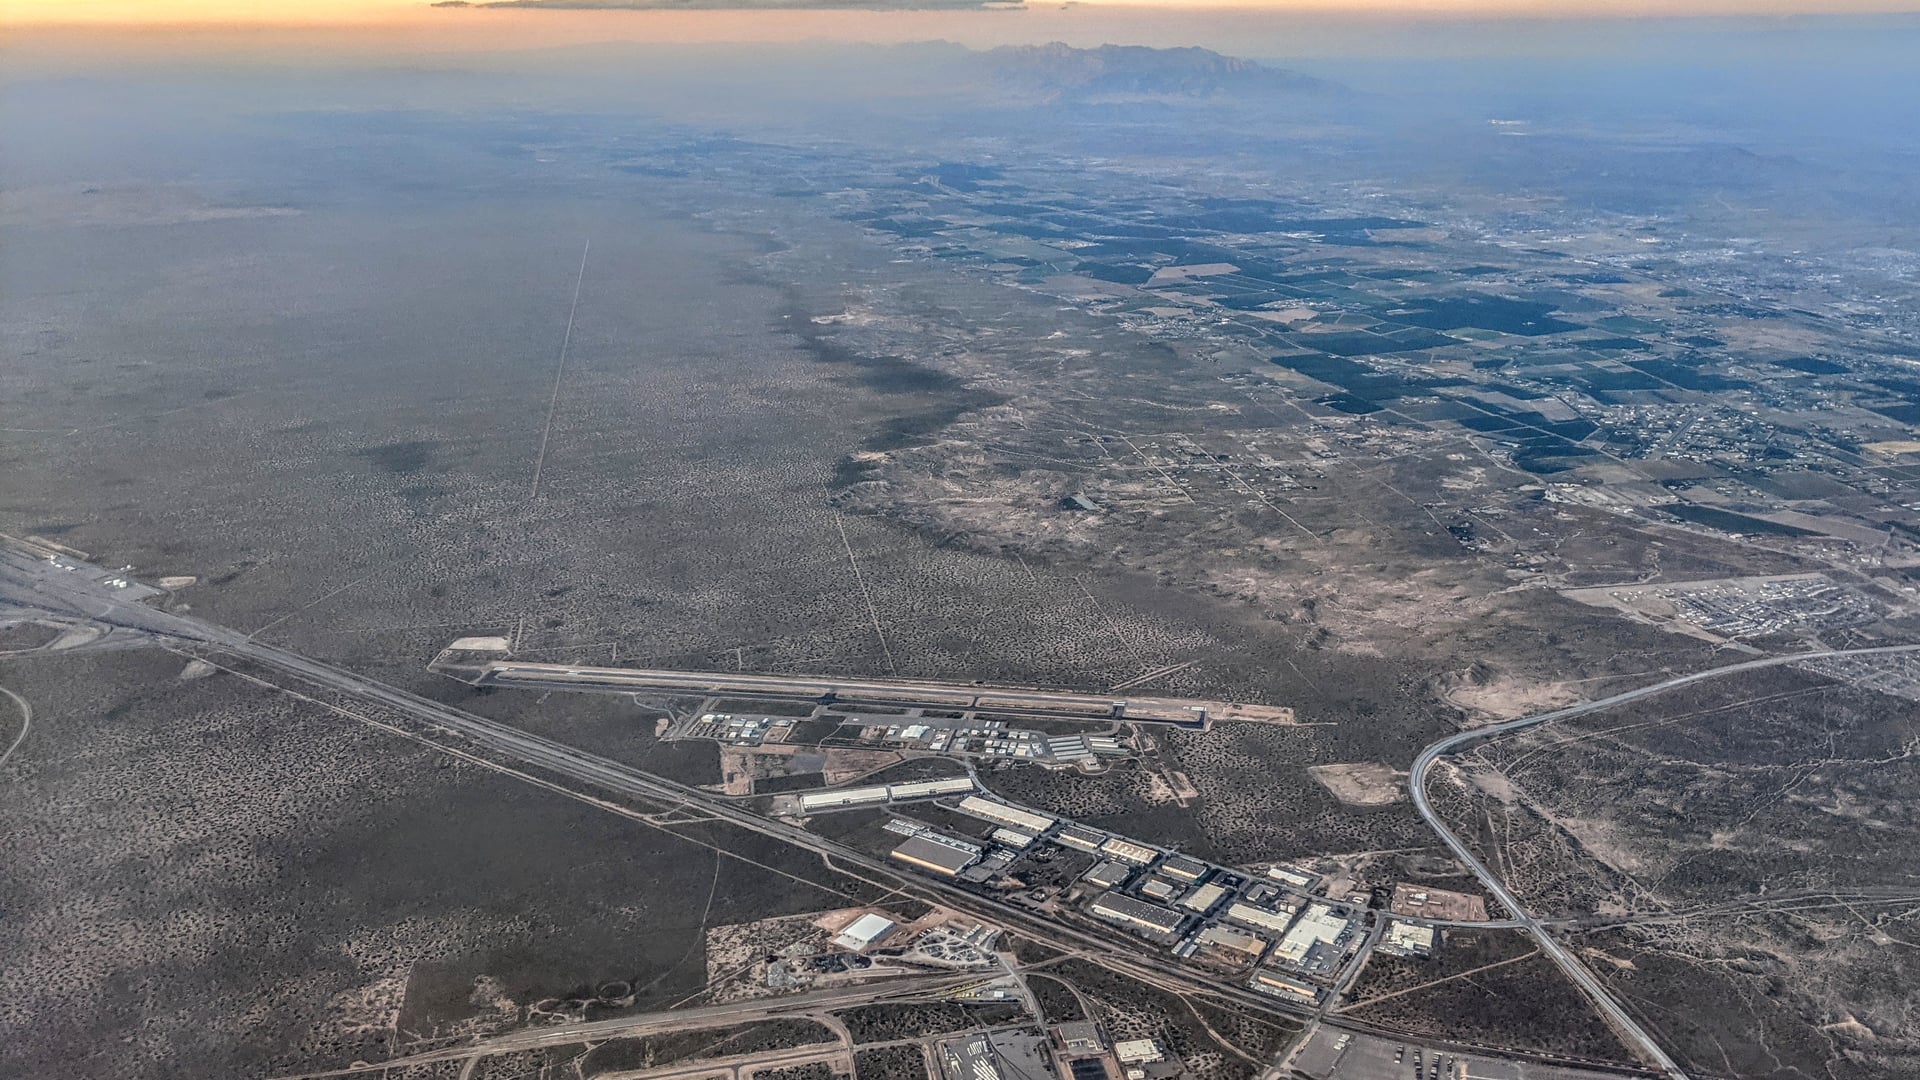
That's where this connects to the AI buildout. In my column on the Kansas City Fed president asking whether AI is becoming "too big to fail," I noted that rising bond yields add pressure. We're already seeing signs of it. About $18 billion of loans financing an Oracle (ORCL) data center in New Mexico were quoted at 89 to 91 cents on the dollar as the banks arranging them struggled to sell them. CoreWeave (CRWV) recorded $640 million of net interest expense in its second quarter alone.
Those are the borrowers I'd watch most closely: companies carrying heavy debt while counting on future revenue to service it.
What I'd watch next
Our AI Bubble Index reads 60 today, in the "Heated" range. It tracks seven things, including valuations, insider selling, and customer concentration, but none of them measures credit. So a junk-bond selloff wouldn't show up in the index directly.
The number I'd keep an eye on is the 10-year yield. Mike Reynolds, vice president of investment strategy at Glenmede, told MarketWatch his firm has been "circling 5.5% on the 10-year" as the level where the firm gets more interested in buying. "We're getting there a little more quickly than we thought," he said.
I'd also watch the extra yield investors demand to hold junk bonds over Treasurys. A sustained widening would suggest investors want more compensation for taking credit risk. The 10-year yield tells us about the broader cost of borrowing. Credit spreads help show how much additional pressure risky borrowers face.